Compare options
Debt Consolidation vs. Balance Transfer
7 min read · By the HappyPath editorial team
Published October 22, 2026 · Reviewed October 22, 2026
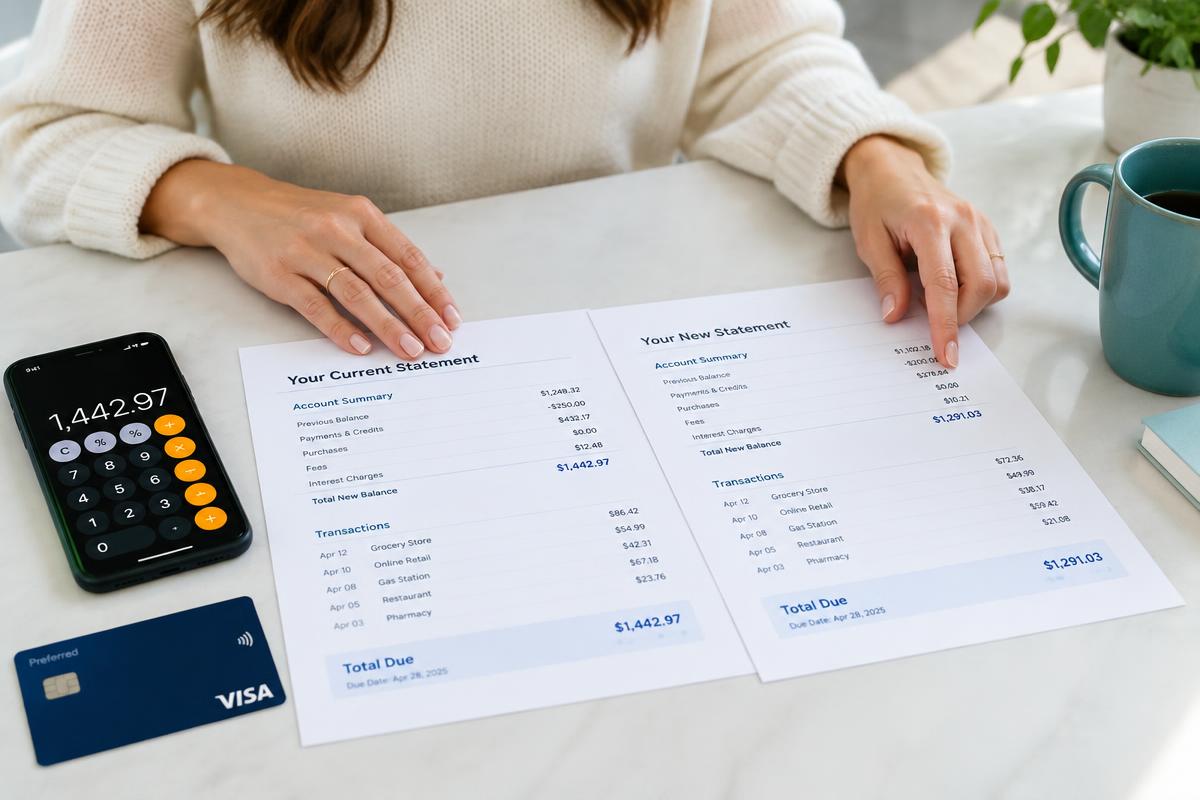
Two of the most common ways to tackle credit card debt are a debt consolidation loan and a balance transfer credit card. Both can reduce what you pay in interest, but they work very differently. Here's an even-handed look at each.
How a balance transfer card works
A balance transfer card lets you move existing card balances to a new card, often with a 0% introductory APR for a limited period — commonly 12 to 21 months. You usually pay a transfer fee of about 3%–5% of the amount moved. When the intro period ends, any remaining balance starts accruing interest at the card's regular variable APR, which is often above 20%.
How a consolidation loan works
A debt consolidation loan is a personal loan used to pay off your cards. You get a fixed APR, a fixed monthly payment and a set term, typically 24 to 84 months. Some lenders charge an origination fee, usually 1%–10%, often deducted from the loan amount.
Side-by-side comparison
| Balance transfer card | Consolidation loan | |
|---|---|---|
| Interest | Often 0% for 12–21 months, then a variable APR | Fixed APR for the full term |
| Upfront cost | Transfer fee, about 3%–5% | Origination fee, 0%–10% depending on lender and credit |
| Payoff date | None required | Set end date, typically 24–84 months |
| Amount | Limited by your credit line | Up to $50,000–$100,000 with some lenders |
| Credit needed | Generally good to excellent for 0% offers | Wider range, with higher APRs for lower scores |
When a balance transfer may be better
- Your balance is modest and you can realistically pay it off before the intro period ends
- You have good to excellent credit and qualify for a long 0% period
- You're disciplined about not adding new charges to the card
Example: moving $5,000 to a card with an 18-month 0% intro APR and a 3% fee costs $150 upfront. Paying about $286 a month clears it before interest kicks in.
When a consolidation loan may be better
- Your balance is large and would take longer than an intro period to repay
- You want a predictable payment and a fixed payoff date
- You don't qualify for a long 0% transfer offer or the credit line is too small
- You have debts across several cards or lenders you want to combine
Risks to watch for
- Balance transfer: a leftover balance at the end of the intro period can face high interest; late payments can sometimes cancel the promotional rate
- Consolidation loan: a high APR or long term can reduce or eliminate savings; origination fees reduce the funds you receive
- Both: running up the old cards again can leave you with more debt than before
How to decide
Start by estimating how long it will take you to pay off the debt. If you can clear it within a 0% intro period, a balance transfer is often the lowest-cost option. If it will take longer, compare the total cost of a fixed-rate loan with what you'd pay after a balance transfer's intro period ends. Pre-qualifying for loans with soft credit checks lets you see real estimated rates before you decide.
Neither option fixes the underlying spending pattern. Pair either one with a budget and a plan for keeping card balances at zero.
Sources
This article is for general educational purposes and isn’t financial, legal or tax advice. Rates, fees and terms vary by lender and borrower; examples are illustrative. HappyPath Financial is a loan marketplace, not a lender, and may be compensated by lenders. See disclosures.